Water-based PUD Market
Report ID: SQMIG15E4072
Report ID: SQMIG15E4072
[email protected]
USA +1 351-333-4748
Report ID:
SQMIG15E4072 |
Region:
Global |
Published Date: July, 2026
Pages:
157
|Tables:
150
|Figures:
78


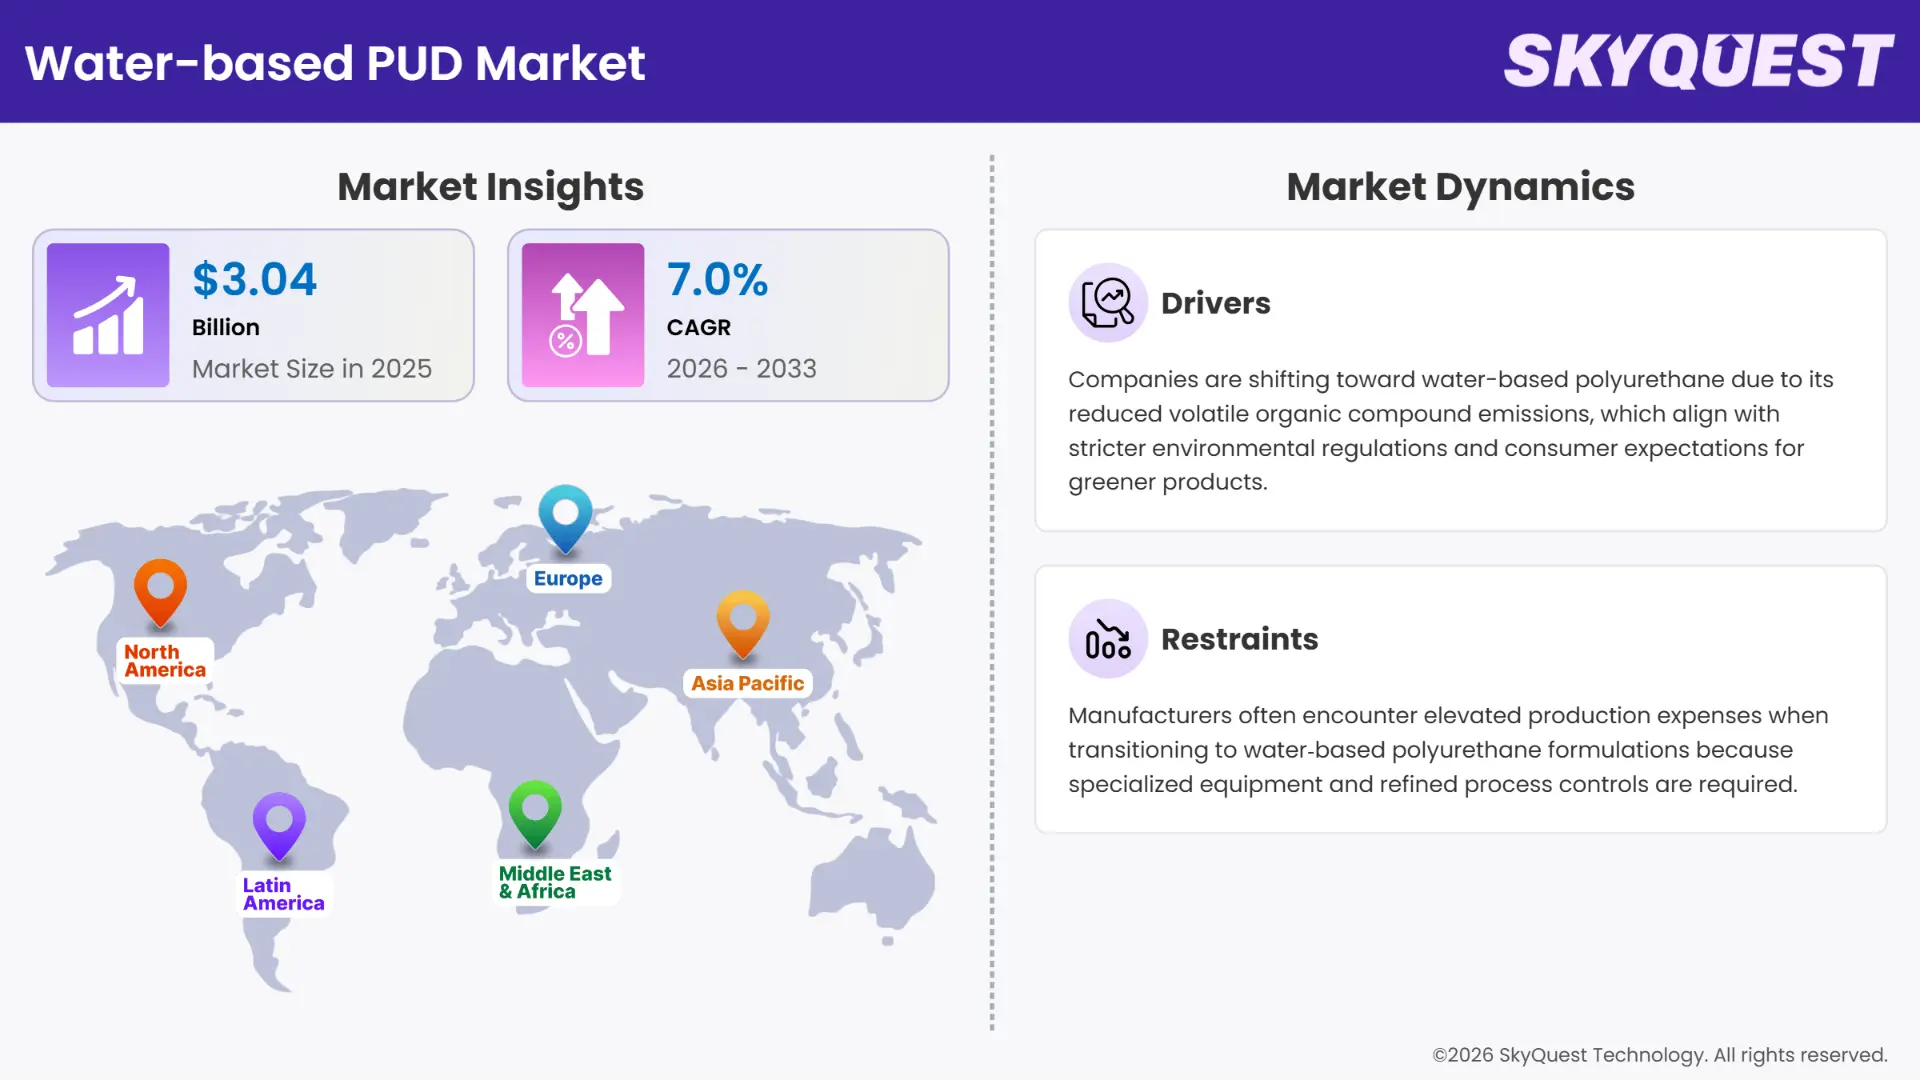
Global Water-Based Pud Market size was valued at USD 2.84 Billion in 2024 and is poised to grow from USD 3.04 Billion in 2025 to USD 5.23 Billion by 2033, growing at a CAGR of 7.0% during the forecast period (2026-2033).
Water-based PUD market trends comprises formulations replacing solvent-borne systems with waterborne carriers providing coating, adhesive, and sealants for automotive, construction, and consumer goods. The importance of it is that strict environmental regulations and consumer demand for low-VOC products have forced manufacturers to embrace water-based chemistries. In the 1990s, the sector grew from niche specialty coatings to a mainstream alternative by the 2010s, with companies like BASF and Covestro introducing large-scale water-based PU lines. This development was further accelerated when EU directives called for reductions of VOCs which forced producers to invest in R&D and to scale production facilities worldwide across continents.
The next big driver of global water-based PUD market growth is the increasing need for high-performance, durable coatings for sustainable construction projects. Green building certifications such as LEED and BREEAM require low-emission materials, and developers are increasingly specifying water-based PU coatings for façades, flooring and roofing membranes that provide abrasion resistance while emitting low levels of VOCs. This cause-effect relationship drives the investment in advanced dispersion technologies that improve film formation and scratch resistance, allowing manufacturers like AkzoNobel to win market share in Europe and Asia. This is leading to changes in supply chains, with raw-material suppliers increasing their inventories of bio-based polyols to satisfy the increasing green demand.
How is AI-driven Automation Influencing Product Innovation in the Water‑Based PUD Market?
AI driven automation is transforming the way formulators are designing water-based PUD market share. By connecting live sensor data to machine learning models, developers can forecast resin stability and adjust raw material ratios without lengthy trial runs. This speeds up the exploration of bio-based polyols and low-VOC additives to respond faster to sustainability demands. Technology also allows for virtual testing that reduces waste and speeds up the time from lab to production. This enables companies to provide more differentiated coating and adhesive solutions, while keeping development cycles lean and responsive.
Wanhua Chemical August 2025 Implemented AI-driven process control to accelerate formulation cycles and improve product consistency to drive market growth on its new water-based resin line.
To get more insights on this market click here to Request a Free Sample Report
Global water-based PUD market is segmented by product type, application, end use industry, solid content, distribution channel and region. Based on product type, the market is segmented into polyester-based PUD, polyether-based PUD, polycarbonate-based PUD and others. Based on application, the market is segmented into coatings, adhesives & sealants, textile finishing, synthetic leather and others. Based on end use industry, the market is segmented into automotive, furniture, construction, textile and others. Based on solid content, the market is segmented into up to 35%, 36–45%, above 45% and others. Based on distribution channel, the market is segmented into direct sales, chemical distributors and others. Based on region, the market is segmented into North America, Europe, Asia Pacific, Latin America and Middle East & Africa.
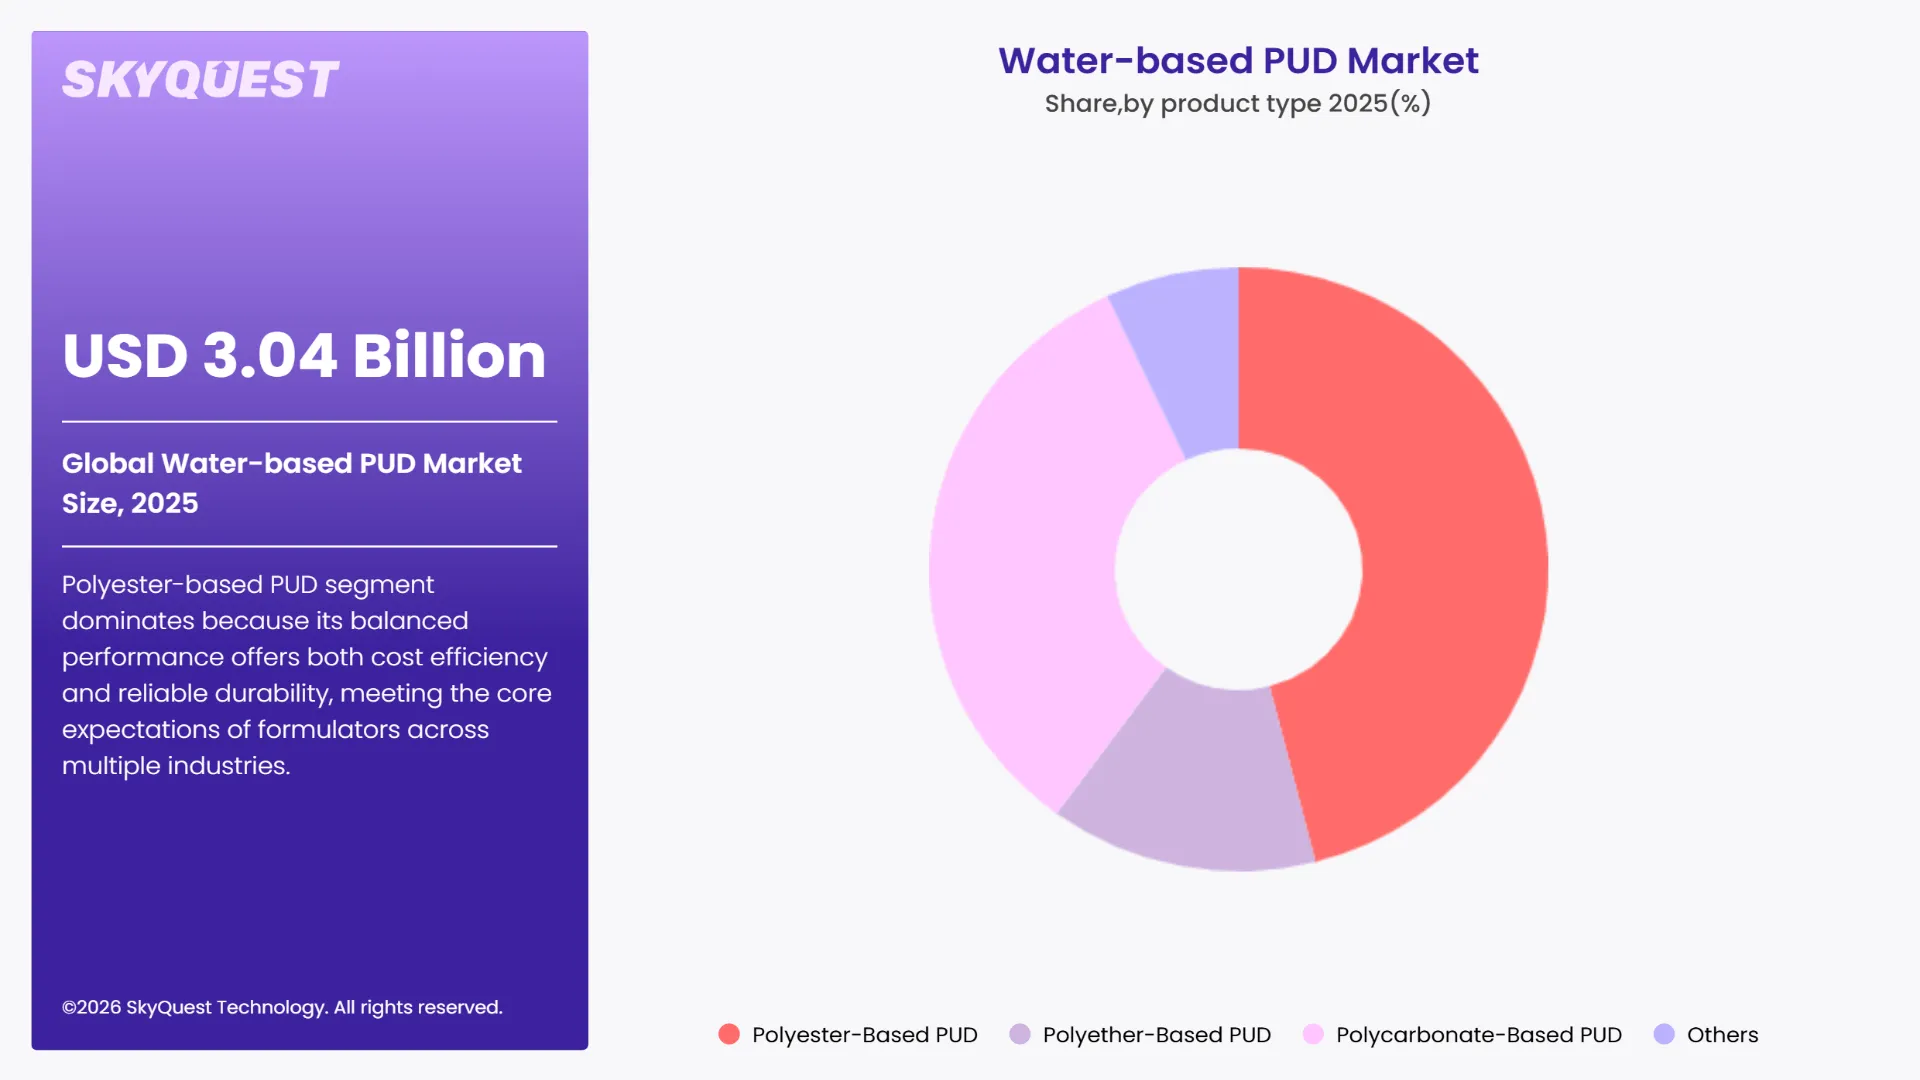
Polyester-based PUD segment dominates because its balanced performance offers both cost efficiency and reliable durability, meeting the core expectations of formulators across multiple industries. The chemistry provides excellent film formation, chemical resistance and weatherability while remaining compatible with water based processes. This combination reduces reliance on solvents and aligns with sustainability targets, driving widespread adoption and reinforcing its leadership within the water based PUD market for diverse end use applications.
However, polyether-based PUD segment is witnessing the strongest growth momentum because its inherent flexibility and superior low temperature performance open new opportunities in emerging sectors such as flexible packaging and renewable energy components. Innovative formulations exploiting these attributes are expanding market reach and creating fresh avenues for product differentiation.
Coatings segment dominates because it serves as the primary demand driver, offering protective and decorative solutions that align with the core benefits of water based PUD technology. Formulators value the ability to achieve high gloss, abrasion resistance and environmental compliance without solvent emissions. This relevance across automotive, construction and consumer goods creates a steady pipeline of projects, cementing coatings as the central application pillar within the water based PUD market.
Meanwhile, textile finishing segment emerges as the fastest growing because its demand for sustainable dyeing and coating processes drives adoption of water based PUDs that deliver softness, crease resistance and environmentally friendly performance. Continuous innovation in fabric treatment is expanding its scope, unlocking new market potential and reinforcing growth prospects for manufacturers.
To get detailed segments analysis, Request a Free Sample Report
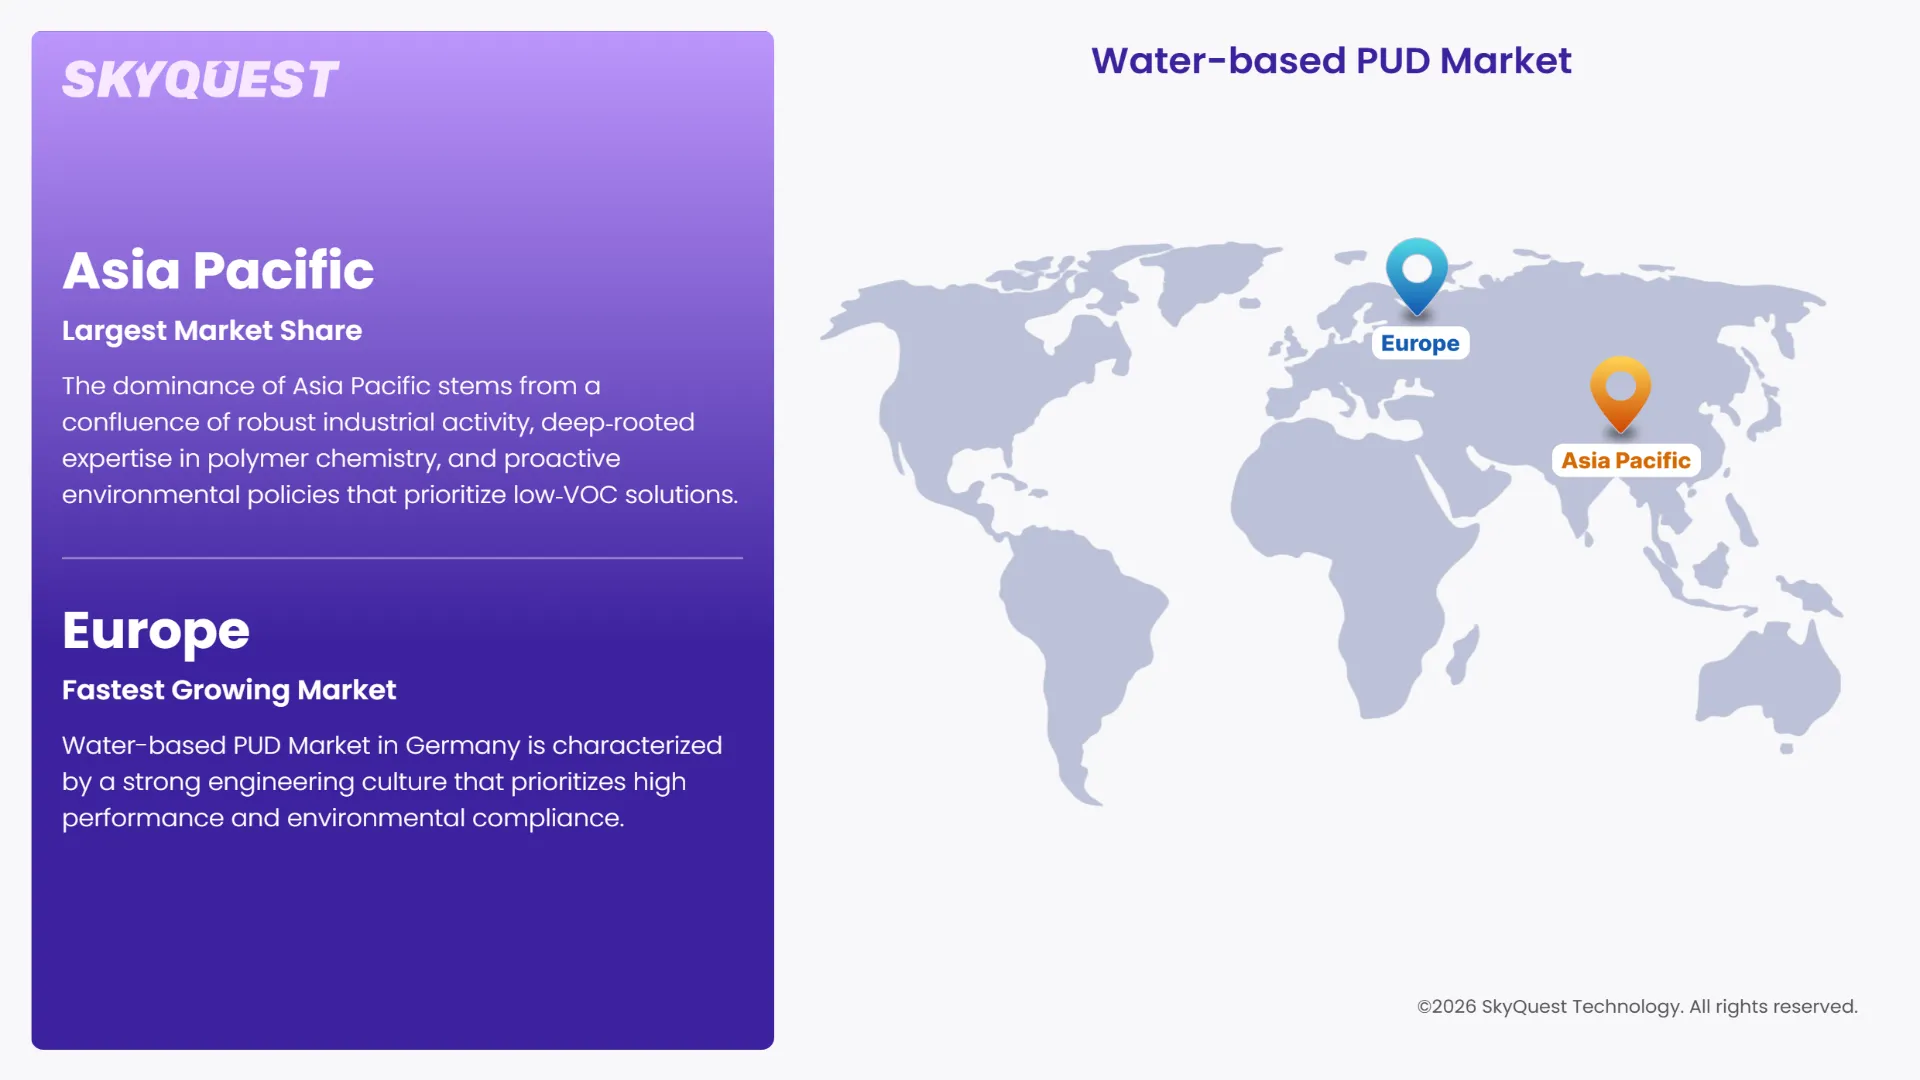
Asia Pacific’s dominance is driven by strong industrial activity, deep-seated expertise in polymer chemistry and progressive environmental regulations that favor low-VOC solutions. The large manufacturers have long supply lines and cheap sources of raw materials, so they are able to sell at competitive prices without sacrificing performance. High demand in the automotive, construction and consumer goods industries continues to drive innovation, with regional partnerships speeding the transfer of technology and customization of products. These factors together create a strong ecosystem that maintains market leadership and attracts global investment.
Water-based PUD market forecast in Japan benefits from a mature coating industry that emphasizes high quality and sustainability. Customer expectations for premium finishes drive continuous refinement of polymer formulations, while stringent environmental guidelines incentivize the shift toward water‑based systems. Collaborative research between industry and academic institutions fosters rapid adoption of advanced technologies, reinforcing Japan’s reputation for precision and reliability in coating applications.
Water-based PUD market outlook in South Korea is propelled by a vibrant manufacturing base that values innovation and eco‑friendly practices. Government incentives for greener production support the transition to water‑based coatings across automotive and electronics sectors. Strong engineering capabilities enable the development of high‑performance blends that meet demanding application requirements, positioning South Korea as a pivotal contributor to regional market depth.
Europe’s rapid growth is fuelled by stringent environmental legislation encouraging low-VOC alternatives, alongside a mature construction market that requires hard-wearing, sustainable finishes. In addition to consumer demand for healthier indoor environments, there is a demand for water-based solutions, and leading chemical producers are investing heavily in research to improve performance attributes such as flexibility and weather resistance. With a strong emphasis on circular economy principles, the region further accelerates adoption as manufacturers align product development with recyclability and resource efficiency goals, creating a dynamic growth environment across key national markets.
Water-based PUD market regional outlook in Germany is characterized by a strong engineering culture that prioritizes high performance and environmental compliance. Leading automotive and industrial coating manufacturers integrate water‑based polymers to meet stringent emission standards, while collaborative innovation clusters advance formulation efficiency. This blend of technical expertise and regulatory alignment solidifies Germany’s position as a dominant force within the European landscape.
Water-based PUD market regional forecast in United Kingdom experiences swift growth due to heightened awareness of sustainable construction practices and regulatory encouragement of low‑VOC products. The sector benefits from a vibrant research ecosystem that partners with industry to accelerate product development. Demand from the refurbishment and infrastructure segments drives rapid uptake, positioning the United Kingdom as a leading growth engine within Europe.
Water-based PUD market analysis in France is emerging as a focus of strategic investment and consumer demand for greener building solutions. Environmental initiatives promote the transition from solvent‑based to water‑based coatings, while niche applications in luxury interiors and heritage restoration create specialized opportunities. Collaborative projects between academic institutions and coating manufacturers nurture innovation, supporting France’s ascent as an emerging market within the region.
North America’s position is bolstered by a mix of advanced research capabilities, demand for high-performance coatings, and a regulatory environment that supports sustainable formulations. Industry-leading water-based technologies deliver superior durability and aesthetics, for everything from automotive to aerospace to commercial construction applications. Consumers’ demand for cleaner indoor air also is pushing manufacturers to expand their water-based offerings. These dynamics combine to support a resilient market path and encourage ongoing adoption across a wide range of applications.
Water-based PUD market penetration in United States reflects a robust ecosystem of innovation and large‑scale manufacturing. Strong demand from automotive and building sectors drives the refinement of high‑solids, low‑VOC formulations. Collaborative initiatives between chemical firms and research institutions accelerate the introduction of next‑generation polymers that balance performance with environmental responsibility, reinforcing the United States’ leadership role.
Water-based PUD industry in Canada benefits from a proactive approach to sustainability and a growing construction industry that values low‑emission coatings. Regional incentives support the development of water‑based technologies tailored to harsh climate conditions, while partnerships with academic centers foster advances in polymer chemistry. These efforts collectively enhance Canada’s contribution to the broader North American market.
To know more about the market opportunities by region and country, click here to
Buy The Complete Report
Growing Preference for Eco-Friendly Finishes
Adoption of Waterborne PU Technologies
Higher Production Costs for Water-Based Systems
Limited Shelf Life of Aqueous Formulations
Request Free Customization of this report to help us to meet your business objectives.
The competitive landscape of the global water‑based PUD market is shaped by aggressive M&A activity, strategic partnerships with coating manufacturers, and rapid tech innovation in bio‑based polyols and nanocomposite dispersions. Recent examples include a major polymer group acquiring a niche PUD developer to broaden its sustainable product line, and a leading adhesive company partnering with a biotech startup to integrate renewable raw materials, accelerating market adoption and differentiating offerings.
Top Player’s Company Profile
Recent Developments in the Water-based PUD Market
SkyQuest’s ABIRAW (Advanced Business Intelligence, Research & Analysis Wing) is our Business Information Services team that Collects, Collates, Correlates, and Analyses the Data collected by means of Primary Exploratory Research backed by robust Secondary Desk research. As per SkyQuest analysis the global water‑based PUD market is being propelled primarily by a growing preference for eco‑friendly finishes, while a secondary boost comes from the expanding adoption of waterborne PU technologies that satisfy design and sustainability demands. The coatings segment continues to dominate because it supplies the core protective and decorative solutions across automotive, construction and consumer goods. Asia Pacific leads the market thanks to strong industrial activity, cost‑effective raw material supply and supportive regulations. However, higher production costs for water‑based systems act as a restraint, limiting adoption in price‑sensitive regions and creating a hurdle for faster market penetration.
| Report Metric | Details |
|---|---|
| Market size value in 2024 | USD 2.84 Billion |
| Market size value in 2033 | USD 5.23 Billion |
| Growth Rate | 7.0% |
| Base year | 2024 |
| Forecast period | (2026-2033) |
| Forecast Unit (Value) | USD Billion |
| Segments covered |
|
| Regions covered | North America (US, Canada), Europe (Germany, France, United Kingdom, Italy, Spain, Rest of Europe), Asia Pacific (China, India, Japan, Rest of Asia-Pacific), Latin America (Brazil, Rest of Latin America), Middle East & Africa (South Africa, GCC Countries, Rest of MEA) |
| Companies covered |
|
| Customization scope | Free report customization with purchase. Customization includes:-
|
To get a free trial access to our platform which is a one stop solution for all your data requirements for quicker decision making. This platform allows you to compare markets, competitors who are prominent in the market, and mega trends that are influencing the dynamics in the market. Also, get access to detailed SkyQuest exclusive matrix.
Table Of Content
Executive Summary
Market overview
Parent Market Analysis
Market overview
Market size
KEY MARKET INSIGHTS
COVID IMPACT
MARKET DYNAMICS & OUTLOOK
Market Size by Region
KEY COMPANY PROFILES
Methodology
For the Water-based PUD Market, our research methodology involved a mixture of primary and secondary data sources. Key steps involved in the research process are listed below:
1. Information Procurement: This stage involved the procurement of Market data or related information via primary and secondary sources. The various secondary sources used included various company websites, annual reports, trade databases, and paid databases such as Hoover's, Bloomberg Business, Factiva, and Avention. Our team did 45 primary interactions Globally which included several stakeholders such as manufacturers, customers, key opinion leaders, etc. Overall, information procurement was one of the most extensive stages in our research process.
2. Information Analysis: This step involved triangulation of data through bottom-up and top-down approaches to estimate and validate the total size and future estimate of the Water-based PUD Market.
3. Report Formulation: The final step entailed the placement of data points in appropriate Market spaces in an attempt to deduce viable conclusions.
4. Validation & Publishing: Validation is the most important step in the process. Validation & re-validation via an intricately designed process helped us finalize data points to be used for final calculations. The final Market estimates and forecasts were then aligned and sent to our panel of industry experts for validation of data. Once the validation was done the report was sent to our Quality Assurance team to ensure adherence to style guides, consistency & design.
Analyst Support
Customization Options
With the given market data, our dedicated team of analysts can offer you the following customization options are available for the Water-based PUD Market:
Product Analysis: Product matrix, which offers a detailed comparison of the product portfolio of companies.
Regional Analysis: Further analysis of the Water-based PUD Market for additional countries.
Competitive Analysis: Detailed analysis and profiling of additional Market players & comparative analysis of competitive products.
Go to Market Strategy: Find the high-growth channels to invest your marketing efforts and increase your customer base.
Innovation Mapping: Identify racial solutions and innovation, connected to deep ecosystems of innovators, start-ups, academics, and strategic partners.
Category Intelligence: Customized intelligence that is relevant to their supply Markets will enable them to make smarter sourcing decisions and improve their category management.
Public Company Transcript Analysis: To improve the investment performance by generating new alpha and making better-informed decisions.
Social Media Listening: To analyze the conversations and trends happening not just around your brand, but around your industry as a whole, and use those insights to make better Marketing decisions.
REQUEST FOR SAMPLE
 REQUEST FREE CUSTOMIZATION
Global Water-Based Pud Market size was valued at USD 2.84 Billion in 2024 and is poised to grow from USD 3.04 Billion in 2025 to USD 5.23 Billion by 2033, growing at a CAGR of 7.0% during the forecast period (2026-2033).
The competitive landscape of the global water‑based PUD market is shaped by aggressive M&A activity, strategic partnerships with coating manufacturers, and rapid tech innovation in bio‑based polyols and nanocomposite dispersions. Recent examples include a major polymer group acquiring a niche PUD developer to broaden its sustainable product line, and a leading adhesive company partnering with a biotech startup to integrate renewable raw materials, accelerating market adoption and differentiating offerings. 'Covestro AG', 'BASF SE', 'Lubrizol Corporation', 'allnex GmbH', 'Wanhua Chemical Group Co., Ltd.', 'Mitsui Chemicals, Inc.', 'LANXESS AG', 'Alberdingk Boley GmbH', 'Michelman, Inc.', 'Stahl Holdings B.V.', 'DIC Corporation', 'Coim Group', 'Perstorp Holding AB', 'Dow Inc.', 'Huntsman Corporation', 'Miwon Specialty Chemical Co., Ltd.', 'Mitsubishi Chemical Group Corporation', 'Reichhold LLC', 'SNF Group', 'Tosoh Corporation'
Companies are shifting toward water-based polyurethane due to its reduced volatile organic compound emissions, which align with stricter environmental regulations and consumer expectations for greener products. This shift encourages manufacturers to invest in research and development of high‑performance formulations, thereby expanding the product portfolio available to end users. As a result, market participants experience increased demand across construction, automotive, and furniture sectors, fostering sustained growth and broader adoption of sustainable coating solutions. Furthermore, the lower health hazards associated with water-based systems improve workplace safety, encouraging broader implementation across large‑scale projects.
Sustainable Coating Regulations: Stringent environmental policies across Europe, North America and emerging markets are compelling manufacturers to adopt low‑VOC, water‑based polyurethane systems. Regulatory bodies are tightening emissions limits for indoor air quality and mandating greener product disclosures, which pushes suppliers to innovate greener chemistries and certify compliance. This regulatory momentum accelerates market adoption, drives R&D investment, and creates a competitive advantage for early adopters that can demonstrate conformity with the evolving sustainability standards throughout the value chain globally across regional markets and industries.
Why does Asia Pacific Dominate the Global Water-based PUD Market? |@12


Want to customize this report? This report can be personalized according to your needs. Our analysts and industry experts will work directly with you to understand your requirements and provide you with customized data in a short amount of time. We offer $1000 worth of FREE customization at the time of purchase.
Feedback From Our Clients


 USA (+1) 351-333-4748

