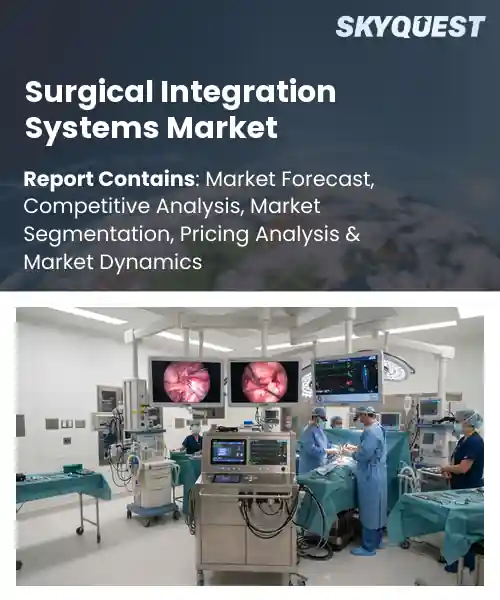
Surgical Integration Systems Market
Report ID: SQMIG35A4589
Report ID: SQMIG35A4589
[email protected]
USA +1 351-333-4748
Report ID:
SQMIG35A4589 |
Region:
Global |
Published Date: September, 2026
Pages:
157
|Tables:
152
|Figures:
78


Global Surgical Integration Systems Market size was valued at USD 3.5 Billion in 2024 and is poised to grow from USD 3.81 Billion in 2025 to USD 7.54 Billion by 2033, growing at a CAGR of 8.9% during the forecast period (2026-2033).
The Global Surgical Integration Systems market encompasses hardware and software platforms that unify imaging, navigation, and robotic components to enable data fusion during operative procedures. Its significance stems from the growing demand for minimally invasive surgeries, where precise spatial awareness reduces complications and shortens hospital stays. Historically, the market emerged in the early 2000s as standalone imaging consoles were coupled with navigation suites, exemplified by the Da Vinci® system’s integration of 3‑D vision and instrument tracking. Over the past decade, adoption accelerated as hospitals pursued cost‑effective ecosystems, a 45 % rise in integrated platform purchases across America between 2015 and 2022. Regulatory endorsement of data interoperability now drives the market’s expansion, because mandates for communication between OR devices compel manufacturers to adopt open‑architecture platforms. This pressure creates opportunities for software vendors that can certify compliance with standards such as IEC 62304, enabling hospitals to upgrade legacy equipment without replacement. An example is the partnership between Medtronic and a cloud‑based analytics firm, which integrated intra‑operative imaging with AI decision support, resulting in a 12 % reduction in operative time for neurosurgical cases. Consequently, clinicians experience improved workflow efficiency, payers observe lower procedural costs, and providers gain a competitive edge by offering interoperable suites.
How is AI-driven automation reshaping the surgical integration systems market?
AI driven automation is redefining surgical integration systems by linking imaging, navigation and robotics into seamless workflows. Real time data processing enables surgeons to overlay patient anatomy on live video, reducing manual adjustments and improving precision. Vendors now embed machine learning algorithms that anticipate instrument positioning and suggest optimal camera angles, which shortens procedure time and lowers fatigue. Hospitals are adopting modular platforms that can scale across specialties, creating a more flexible infrastructure. The market is shifting from isolated devices to interconnected ecosystems, fostering collaboration between device makers, software developers and clinical teams.Intuitive Surgical March 2024, introduced an AI powered workflow assistant for its da Vinci platform that automatically aligns imaging data with robotic instruments, streamlining setup and reducing intra operative pauses. This advancement demonstrates how AI driven automation accelerates adoption and boosts efficiency across operating rooms.
Market snapshot - (2026-2033)
Global Market Size
USD 3.5 Billion
Largest Segment
Operating Room Integration Systems
Fastest Growth
Operating Room Integration Systems
Growth Rate
8.9% CAGR
To get more insights on this market click here to Request a Free Sample Report
Global surgical integration systems market is segmented by system type, component, technology, application, end-use industry and region. Based on system type, the market is segmented into Operating Room Integration Systems, Video Integration Systems, Audio Integration Systems, Surgical Information Management Systems and Others. Based on component, the market is segmented into Hardware, Software and Services. Based on technology, the market is segmented into Wired Systems, Wireless Systems, Cloud-Enabled Systems and Others. Based on application, the market is segmented into General Surgery, Orthopedic Surgery, Neurosurgery, Cardiovascular Surgery, Gynecological Surgery and Others. Based on end-use industry, the market is segmented into Hospitals, Ambulatory Surgical Centers, Specialty Surgical Centers, Academic Medical Centers and Others. Based on region, the market is segmented into North America, Europe, Asia Pacific, Latin America and Middle East & Africa.
Operating Room Integration Systems segment dominates because it serves as the central nervous system of modern operating suites, linking surgical lights, imaging devices, and patient monitors into a unified workflow. Hospitals prioritize seamless orchestration to reduce procedure time and enhance safety, prompting procurement decisions that favor comprehensive OR platforms. Vendors that provide intuitive user interfaces, robust connectivity, and scalable architecture attract the majority of capital allocations, reinforcing this segment’s leading position.
However, Video Integration Systems are witnessing the strongest growth momentum as surgeons increasingly rely on high definition visual feeds for precision tasks. Advances in display technology and the integration of augmented reality overlay are expanding adoption across specialties, prompting hospitals to upgrade their visual infrastructure. This rapid uptake fuels broader market expansion and creates new avenues for innovative solution providers.
Hardware segment dominates because the physical reliability and interoperability of devices underpin the entire integration ecosystem, making robust equipment a prerequisite for any surgical suite upgrade. Decision makers concentrate on durable consoles, seamless cabling, and certified interfaces to minimize downtime and ensure patient safety. Consequently, manufacturers that deliver rugged plug and play solutions capture the bulk of procurement budgets, cementing hardware’s preeminent role in market dynamics.
Meanwhile, Software is emerging as the key high growth area as hospitals adopt AI driven analytics and cloud based orchestration tools. The shift toward digital workflow optimization fuels demand for modular interoperable applications that can integrate data streams across devices. This surge accelerates market expansion, inviting new entrants and driving investment in innovative software platforms.
To get detailed segments analysis, Request a Free Sample Report
The region benefits from a mature healthcare ecosystem that places a premium on cutting‑edge operative environments. Extensive capital availability and strong reimbursement mechanisms encourage hospitals to invest in comprehensive integration platforms that connect imaging, navigation and data analytics. Leading technology manufacturers maintain R&D hubs and strategic partnerships with major academic medical centers, fostering rapid adoption of interoperable solutions. Moreover, a culture of continuous clinical improvement drives demand for systems that enhance workflow efficiency, patient safety and outcomes, reinforcing North America’s preeminent market position.
Surgical Integration Systems Market in the United States thrives on a confluence of sophisticated hospital networks, robust venture capital support and a regulatory framework that rewards innovation. Healthcare providers prioritize seamless data exchange across operating rooms, prompting widespread implementation of integrated platforms. Collaborative initiatives between device makers and leading surgical institutes accelerate customization of solutions to meet complex clinical needs, solidifying the United States as a benchmark for advanced surgical integration.
Surgical Integration Systems Market in Canada is propelled by strong public health investment and a strategic emphasis on modernizing surgical suites. Provincial health authorities encourage adoption of interoperable technologies to improve resource utilization and patient outcomes. Partnerships between local research institutions and global technology firms enable tailored integration solutions that address the specific workflow challenges of Canadian hospitals, fostering steady growth in the market.
Europe’s expansion is anchored by a harmonized regulatory environment that facilitates cross‑border technology transfer and standardization. Deeply integrated research ecosystems and a tradition of collaborative clinical trials nurture continuous innovation in surgical connectivity. Reimbursement policies across major economies increasingly recognize the value of integrated systems for reducing procedural times and complications. Additionally, a strong focus on digital health strategies within national health services accelerates procurement of platforms that unify imaging, navigation and analytics, positioning Europe as a dynamic growth region.
Surgical Integration Systems Market in Germany benefits from a robust industrial base and a healthcare system committed to precision medicine. Leading hospitals collaborate closely with engineering firms to co‑develop platforms that seamlessly link diagnostic imaging with intra‑operative guidance. The emphasis on evidence‑based practice drives demand for solutions that enhance procedural accuracy and data-driven decision making, reinforcing Germany’s dominant market role.
Surgical Integration Systems Market in the United Kingdom is experiencing swift momentum due to national initiatives that prioritize digital transformation of operating theatres. NHS trusts are actively deploying integrated platforms to streamline workflows and improve patient pathways. Strong academic‑clinical partnerships foster rapid testing and scaling of innovative solutions, positioning the United Kingdom as a leading growth engine within Europe.
Surgical Integration Systems Market in France is emerging through focused governmental support for healthcare modernization and a growing network of specialized surgical centers. Collaborative projects between French biotech firms and multinational technology providers accelerate the introduction of integrated operating room solutions. This nurturing environment is fostering increasing adoption of platforms that align with France’s strategic vision for advanced surgical care.
Asia Pacific is advancing its market stance through a blend of rising surgical volumes and proactive government policies aimed at modernizing clinical infrastructure. Investment in smart operating rooms and strategic alliances with global technology leaders enable rapid diffusion of integrated solutions across diverse healthcare settings. The region’s emphasis on training and skill development ensures that clinicians can effectively leverage sophisticated platforms, thereby elevating procedural efficiency and patient safety. Collectively, these dynamics are elevating Asia Pacific’s role in the global landscape.
Surgical Integration Systems Market in Japan is driven by a culture of meticulous clinical practice and a national agenda focused on digital health integration. Leading medical universities partner with equipment manufacturers to create seamless interfaces that link pre‑operative planning with real‑time operative guidance. Government incentives for advanced surgical technologies further stimulate adoption, positioning Japan as a key contributor to regional market growth.
Surgical Integration Systems Market in South Korea is propelled by aggressive investment in healthcare innovation and a fast‑adopting clinical community. Collaborative ecosystems between biotech startups and established device firms foster rapid development of interoperable platforms tailored to high‑throughput surgical environments. National health policies that endorse technology‑enabled care support widespread deployment, reinforcing South Korea’s expanding influence in the Asia Pacific market.
To know more about the market opportunities by region and country, click here to
Buy The Complete Report
Advancing Minimally Invasive Technologies
Growing Demand for Integrated OR Solutions
High Initial Capital Investment
Complex Regulatory Compliance Requirements
Request Free Customization of this report to help us to meet your business objectives.
The Global Surgical Integration Systems market is shaped by intense competition among established OEMs and emerging platform providers. Recent M&A such as Siemens Healthineers’ acquisition of Corindus in 2020 and strategic alliances like Intuitive Surgical’s partnership with Google Cloud in 2022 accelerate data‑driven OR solutions. Continuous tech innovation, including AI‑based workflow orchestration and unified device connectivity, drives differentiation and market positioning.
Top Player’s Company Profile
Recent Developments
SkyQuest’s ABIRAW (Advanced Business Intelligence, Research & Analysis Wing) is our Business Information Services team that Collects, Collates, Correlates, and Analyses the Data collected by means of Primary Exploratory Research backed by robust Secondary Desk research. As per SkyQuest analysis, the market is propelled primarily by the surge in minimally invasive surgical techniques that demand seamless coordination of imaging, navigation and instrument control, while hospitals are also accelerating purchases of integrated OR solutions to streamline workflows and improve outcomes; the Operating Room Integration Systems segment remains the clear leader because it acts as the central hub of modern suites, and North America dominates the landscape thanks to mature infrastructure, robust reimbursement and strong R&D investment; however, the high upfront capital required for hardware, software and connectivity upgrades continues to restrain adoption in smaller facilities, tempering overall growth pace.
| Report Metric | Details |
|---|---|
| Market size value in 2024 | USD 3.5 Billion |
| Market size value in 2033 | USD 7.54 Billion |
| Growth Rate | 8.9% |
| Base year | 2024 |
| Forecast period | (2026-2033) |
| Forecast Unit (Value) | USD Billion |
| Segments covered |
|
| Regions covered | North America (US, Canada), Europe (Germany, France, United Kingdom, Italy, Spain, Rest of Europe), Asia Pacific (China, India, Japan, Rest of Asia-Pacific), Latin America (Brazil, Rest of Latin America), Middle East & Africa (South Africa, GCC Countries, Rest of MEA) |
| Companies covered |
|
| Customization scope | Free report customization with purchase. Customization includes:-
|
To get a free trial access to our platform which is a one stop solution for all your data requirements for quicker decision making. This platform allows you to compare markets, competitors who are prominent in the market, and mega trends that are influencing the dynamics in the market. Also, get access to detailed SkyQuest exclusive matrix.
Table Of Content
Executive Summary
Market overview
Parent Market Analysis
Market overview
Market size
KEY MARKET INSIGHTS
COVID IMPACT
MARKET DYNAMICS & OUTLOOK
Market Size by Region
KEY COMPANY PROFILES
Methodology
For the Surgical Integration Systems Market, our research methodology involved a mixture of primary and secondary data sources. Key steps involved in the research process are listed below:
1. Information Procurement: This stage involved the procurement of Market data or related information via primary and secondary sources. The various secondary sources used included various company websites, annual reports, trade databases, and paid databases such as Hoover's, Bloomberg Business, Factiva, and Avention. Our team did 45 primary interactions Globally which included several stakeholders such as manufacturers, customers, key opinion leaders, etc. Overall, information procurement was one of the most extensive stages in our research process.
2. Information Analysis: This step involved triangulation of data through bottom-up and top-down approaches to estimate and validate the total size and future estimate of the Surgical Integration Systems Market.
3. Report Formulation: The final step entailed the placement of data points in appropriate Market spaces in an attempt to deduce viable conclusions.
4. Validation & Publishing: Validation is the most important step in the process. Validation & re-validation via an intricately designed process helped us finalize data points to be used for final calculations. The final Market estimates and forecasts were then aligned and sent to our panel of industry experts for validation of data. Once the validation was done the report was sent to our Quality Assurance team to ensure adherence to style guides, consistency & design.
Analyst Support
Customization Options
With the given market data, our dedicated team of analysts can offer you the following customization options are available for the Surgical Integration Systems Market:
Product Analysis: Product matrix, which offers a detailed comparison of the product portfolio of companies.
Regional Analysis: Further analysis of the Surgical Integration Systems Market for additional countries.
Competitive Analysis: Detailed analysis and profiling of additional Market players & comparative analysis of competitive products.
Go to Market Strategy: Find the high-growth channels to invest your marketing efforts and increase your customer base.
Innovation Mapping: Identify racial solutions and innovation, connected to deep ecosystems of innovators, start-ups, academics, and strategic partners.
Category Intelligence: Customized intelligence that is relevant to their supply Markets will enable them to make smarter sourcing decisions and improve their category management.
Public Company Transcript Analysis: To improve the investment performance by generating new alpha and making better-informed decisions.
Social Media Listening: To analyze the conversations and trends happening not just around your brand, but around your industry as a whole, and use those insights to make better Marketing decisions.
REQUEST FOR SAMPLE
 REQUEST FREE CUSTOMIZATION


Want to customize this report? This report can be personalized according to your needs. Our analysts and industry experts will work directly with you to understand your requirements and provide you with customized data in a short amount of time. We offer $1000 worth of FREE customization at the time of purchase.
Feedback From Our Clients


 USA (+1) 351-333-4748

