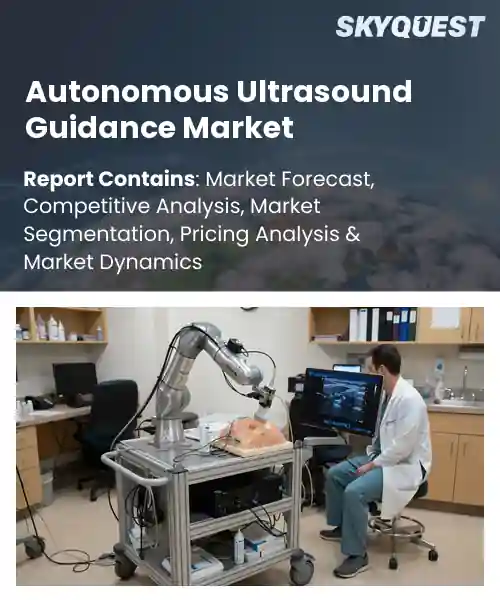
Autonomous Ultrasound Guidance Market

Report ID: SQMIG35A4413

[email protected]
USA +1 351-333-4748

Autonomous Ultrasound Guidance Market Size, Share, and Growth Analysis

Autonomous Ultrasound Guidance Market

Autonomous Ultrasound Guidance Market By Offering (Hardware, Software, Services), By Technology (AI-Based Image Guidance, Robotic Ultrasound Guidance, Navigation & Tracking Systems), By Application, By End User, By Region - Industry Forecast 2026-2033


Report ID: SQMIG35A4413 | Region: Global | Published Date: August, 2026
Pages: 157 |Tables: 121 |Figures: 77

Format - word format excel data power point presentation

Autonomous Ultrasound Guidance Market Insights

Global Autonomous Ultrasound Guidance Market size was valued at USD 1.28 Billion in 2024 and is poised to grow from USD 1.52 Billion in 2025 to USD 5.99 Billion by 2033, growing at a CAGR of 18.7% during the forecast period (2026-2033).

The global autonomous ultrasound guidance market comprises hardware, software and AI‑driven platforms that enable clinicians to acquire, interpret and act on sonographic images without manual probe manipulation. Its importance stems from the need to reduce operator dependency, shorten exam times and expand access to imaging in remote or underserved settings. The market originated in research labs during the early 2010s, progressed through prototype trials in obstetrics and emergency medicine, and today features commercial products such as Siemens’ AI‑Assisted Scan and Philips’ eProbe. Adoption accelerated as hospitals pursued cost‑efficient workflow automation and as tele‑medicine platforms demanded image quality across dispersed providers. The principal catalyst fueling the market’s expansion is the convergence of AI analytics with point‑of‑care imaging, which translates to diagnostic confidence and lower staffing burdens. As AI algorithms mature, they can autonomously adjust probe position, recognize anatomical landmarks and flag pathology, thereby enabling operators such as paramedics to perform cardiac or abdominal scans in pre‑hospital scenarios. This capability reduces patient transfer delays and improves triage accuracy, creating demand from emergency services, military field hospitals and rural clinics. Consequently, vendors are investing in modular, cloud‑connected systems that integrate with electronic health records, opening revenue streams through subscription‑based analytics and data‑service contracts.

How is AI-driven automation impacting the autonomous ultrasound guidance market?

AI-driven automation is reshaping autonomous ultrasound guidance by embedding intelligent image acquisition, real‑time analysis and robotic positioning into a single workflow. The technology reduces reliance on highly trained sonographers, enabling consistent scan quality across diverse settings and expanding access in rural and underserved areas. Recent research demonstrates fully autonomous robotic systems capable of scanning thyroid regions without human assistance, highlighting the feasibility of hands‑free procedures. These advances are accelerating adoption as healthcare providers seek to address workforce shortages while maintaining diagnostic accuracy. The market is therefore experiencing heightened interest from manufacturers and clinicians alike, driven by the promise of faster examinations, lower costs and improved patient experiences.GE Healthcare, March 2025, launched an autonomous ultrasound platform that integrates AI‑guided probe navigation with automated image interpretation, illustrating how AI‑driven automation is enhancing efficiency and supporting the market’s rapid expansion.

Market snapshot - (2026-2033)

Global Market Size

USD 1.28 Billion

Largest Segment

Hardware

Fastest Growth

Software

Growth Rate

18.7% CAGR

Autonomous Ultrasound Guidance Market ($ Bn)
Country Share for North America Region (%)

To get more insights on this market click here to Request a Free Sample Report

Autonomous Ultrasound Guidance Market Segments Analysis

Global autonomous ultrasound guidance market is segmented by offering, technology, application, end user and region. Based on offering, the market is segmented into Hardware, Software and Services. Based on technology, the market is segmented into AI-Based Image Guidance, Robotic Ultrasound Guidance and Navigation & Tracking Systems. Based on application, the market is segmented into Diagnostic Imaging, Interventional Procedures, Obstetrics & Gynecology, Cardiology, Musculoskeletal Imaging and Emergency & Critical Care. Based on end user, the market is segmented into Hospitals, Diagnostic Imaging Centers, Ambulatory Surgical Centers and Research & Academic Institutes. Based on region, the market is segmented into North America, Europe, Asia Pacific, Latin America and Middle East & Africa.

How is AI based image guidance reshaping clinical workflows in autonomous ultrasound?

AI based Image Guidance segment dominates because it directly addresses the core challenge of real time anatomical interpretation, enabling autonomous systems to make precise probe adjustments without human intervention. Its integration of deep learning models with ultrasound signal processing creates a feedback loop that continuously refines image quality, fostering clinician confidence and accelerating adoption across diverse care settings. The ability to automate diagnostic decision points drives its leadership in the market.

Meanwhile, Robotic Ultrasound Guidance segment emerges as the fastest growing area because advances in compact actuator design and control algorithms are lowering barriers to deployment in care environments. These innovations expand the reach of autonomous scanning to remote clinics and emergency units, creating new revenue streams and stimulating broader market expansion.

what impact does diagnostic imaging have on the adoption of autonomous ultrasound systems?

Diagnostic Imaging segment dominates because it provides the primary clinical justification for autonomous ultrasound, delivering high volume, routine examinations where consistency and speed are paramount. The need for standardized image acquisition across large patient cohorts drives manufacturers to embed autonomous capabilities, while clinicians value reduced operator variability, reinforcing its central role in market leadership. Because these examinations serve as first line screening tools, the pressure to improve throughput without compromising diagnostic accuracy fuels investment in self navigating probes.

On the other hand, Interventional Procedures segment is witnessing the strongest growth momentum because autonomous ultrasound is increasingly being integrated into image guided therapies, where real time needle placement and tissue targeting demand precise, hands free imaging. This convergence expands the technology’s value proposition beyond diagnosis, attracting proceduralists and driving investment in specialized probe designs, thereby accelerating market diversification and opening new revenue channels.

Autonomous Ultrasound Guidance Market By Offering

To get detailed segments analysis, Request a Free Sample Report

Autonomous Ultrasound Guidance Market Regional Insights

Why does North America Dominate the Global Autonomous Ultrasound Guidance Market?

The region benefits from a mature healthcare ecosystem where leading academic hospitals and large health systems rapidly adopt advanced imaging solutions. Robust funding mechanisms and a proactive regulatory environment encourage integration of AI‑driven guidance tools. Presence of pioneering medical device manufacturers and extensive research collaborations accelerates technology refinement. High clinician awareness and patient demand for precision diagnostics further embed autonomous ultrasound into routine practice. Integrated payer structures support reimbursement pathways, reinforcing market confidence and fostering continuous investment in next‑generation ultrasound platforms.

United States Autonomous Ultrasound Guidance Market

Autonomous Ultrasound Guidance Market in the United States thrives on strong venture capital support for AI startups and close partnerships between technology firms and clinical institutions. The ecosystem emphasizes real‑world evidence generation, expediting clinician acceptance. Advanced training programs and digital health initiatives streamline workflow adoption, while progressive reimbursement policies reduce financial barriers for providers seeking automated imaging solutions.

Canada Autonomous Ultrasound Guidance Market

Autonomous Ultrasound Guidance Market in Canada is bolstered by a collaborative health research landscape and public health funding that prioritizes innovative diagnostic tools. Provincial health authorities promote pilot implementations within both urban and remote care settings, enhancing access to high‑quality imaging. Strong academic ties and a focus on patient‑centered outcomes drive clinician enthusiasm for autonomous ultrasound technologies.

What is Driving the Rapid Expansion of Autonomous Ultrasound Guidance Market in Europe?

Europe’s expansion is driven by unified regulatory standards that simplify market entry across member states, encouraging cross‑border technology diffusion. Deep integration of academic research with industrial expertise fuels continuous innovation in AI algorithms. Health systems increasingly value cost‑effective diagnostic pathways, prompting adoption of autonomous ultrasound to improve efficiency. Strong commitment to digital health transformation across the region supports interoperability and data‑driven clinical decision making. Collaborative funding mechanisms and patient‑focused healthcare policies further accelerate uptake, positioning Europe as a hub for next‑generation imaging solutions.

Germany Autonomous Ultrasound Guidance Market

Autonomous Ultrasound Guidance Market in Germany benefits from a dense network of research hospitals and engineering firms that co‑develop sophisticated imaging platforms. National health insurance frameworks endorse technology that enhances diagnostic accuracy, facilitating broad clinical integration. Emphasis on rigorous clinical validation ensures clinician confidence, while manufacturing excellence supports export potential, reinforcing Germany’s leading role in the European market.

United Kingdom Autonomous Ultrasound Guidance Market

Autonomous Ultrasound Guidance Market in the United Kingdom experiences swift growth through National Health Service initiatives that prioritize AI‑enhanced diagnostics. Early adoption pilots in primary and secondary care settings demonstrate workflow efficiencies, prompting wider rollout. Strong academic clusters and industry partnerships accelerate algorithm refinement, while policy incentives encourage investment in autonomous imaging solutions, positioning the United Kingdom as a dynamic growth engine within Europe.

France Autonomous Ultrasound Guidance Market

Autonomous Ultrasound Guidance Market in France is emerging as health authorities endorse innovative diagnostic tools to improve patient pathways. Collaborative projects between French biotech firms and university hospitals drive tailored AI solutions for diverse clinical scenarios. Reimbursement reforms that reward value‑based care create favorable conditions for autonomous ultrasound adoption, fostering a fertile environment for market expansion.

How is Asia Pacific Strengthening its Position in Autonomous Ultrasound Guidance Market?

Asia Pacific leverages rapid digital health adoption and growing demand for accessible diagnostic services to advance autonomous ultrasound penetration. Strategic government initiatives promote AI integration in healthcare, while rising awareness of early disease detection fuels clinician interest. Regional manufacturers combine cost‑efficiency with advanced engineering, enabling scalable solutions for both urban hospitals and remote clinics. Collaborative ecosystems linking technology startups, academic institutions, and health providers accelerate knowledge transfer, positioning the region as a burgeoning hub for autonomous imaging innovation.

Japan Autonomous Ultrasound Guidance Market

Autonomous Ultrasound Guidance Market in Japan is propelled by a strong tradition of precision medicine and a healthcare system that values technological advancement. Partnerships between leading electronics firms and medical centers foster development of compact, AI‑driven devices suited for diverse clinical environments. Government incentives encouraging AI research amplify clinical adoption, while clinician training programs ensure seamless integration into routine practice.

South Korea Autonomous Ultrasound Guidance Market

Autonomous Ultrasound Guidance Market in South Korea benefits from a vibrant biotech sector and proactive health policy that supports AI deployment in diagnostics. Close collaboration between manufacturers and university hospitals drives rapid prototyping and validation of autonomous systems. Emphasis on telemedicine and remote monitoring expands market reach, allowing high‑quality imaging to serve both metropolitan and underserved populations.

Autonomous Ultrasound Guidance Market By Geography
  • Largest
  • Fastest

To know more about the market opportunities by region and country, click here to
Buy The Complete Report

Autonomous Ultrasound Guidance Market Dynamics

Drivers

Increasing Demand for Point-of-Care Imaging

  • Healthcare providers are increasingly adopting autonomous ultrasound systems to deliver diagnostics at the bedside, reducing reliance on centralized imaging facilities. This shift enables clinicians to obtain immediate visual feedback, thereby improving patient throughput and clinical decision‑making. The convenience of point‑of‑care imaging also supports resource‑limited environments where traditional ultrasound expertise may be scarce, fostering broader acceptance of autonomous guidance technology across diverse care settings. Consequently, hospitals view autonomous ultrasound as a strategic asset that aligns with initiatives to enhance operational efficiency while maintaining diagnostic quality, prompting increased procurement and integration efforts.

Advancements In AI-Driven Navigation Algorithms

  • Recent breakthroughs in artificial intelligence have refined real‑time image interpretation, enabling autonomous ultrasound platforms to accurately identify anatomical landmarks without operator assistance. These algorithms continuously learn from diverse datasets, improving robustness across patient populations and clinical scenarios. Enhanced precision reduces the likelihood of diagnostic errors and shortens examination times, making the technology attractive to both academic centers and community clinics. Consequently, clinicians are more inclined to trust and integrate autonomous guidance solutions into routine workflows, driving broader significant market adoption.

Restraints

High Initial Capital Investment

  • The acquisition cost of autonomous ultrasound systems remains substantially higher than conventional handheld devices, encompassing sophisticated sensors, AI processors, and integrated robotics. Health institutions must allocate considerable budgetary resources for purchase, installation, and staff training, which can strain financial planning, particularly in low‑resource settings. This economic hurdle often leads organizations to postpone adoption until clear cost‑benefit evidence emerges or until funding mechanisms become more favorable, thereby tempering the pace of market expansion. Additionally, the need for periodic software upgrades and maintenance contracts adds recurring expenses that further deter immediate investment.

Regulatory Approval Complexity

  • Autonomous ultrasound devices must satisfy stringent regulatory frameworks that assess safety, algorithmic transparency, and clinical efficacy across multiple jurisdictions. The requirement for extensive pre‑market clinical validation studies prolongs time‑to‑approval, while differing regional standards create additional compliance burdens for manufacturers. These procedural intricacies elevate development costs and introduce uncertainty regarding market entry timelines. Consequently, manufacturers may prioritize markets with clearer pathways, leaving other regions underserved and slowing global market diffusion. Ongoing software updates to meet evolving standards also demand continuous regulatory documentation, further delaying rollouts.

Request Free Customization of this report to help us to meet your business objectives.

Autonomous Ultrasound Guidance Market Competitive Landscape

The competitive landscape is shaped by rapid tech innovation and strategic alliances, with leading firms pursuing M&A to integrate AI imaging capabilities, partnering with hospital networks for clinical validation, and launching autonomous scanning robots to differentiate offerings in a market driven by demand for precision diagnostics. Recent collaborations between AI‑focused startups and established device manufacturers illustrate how joint development accelerates time‑to‑market for next‑generation autonomous ultrasound solutions.

  • Auto‑RUSS: Established in 2024, their main objective is to create an autonomous robotic ultrasound scanning pipeline that standardizes image acquisition. Recent development: completed a multi‑center pilot study in 2025 demonstrating reproducible scans across operators, positioning the system for commercial rollout.
  • Ultrasound AI Solutions: Established in 2023, their main objective is to deliver an AI‑driven ultrasound guidance platform that provides real‑time decision support for clinicians. Recent development: secured $50 million Series B funding in early 2026 to expand global deployment and integrate with major imaging hardware partners.

Top Player’s Company Profile

  • GE HealthCare Technologies Inc.
  • Siemens Healthineers AG
  • Koninklijke Philips N.V.
  • Canon Medical Systems Corporation
  • Fujifilm Holdings Corporation
  • Samsung Medison Co., Ltd.
  • Butterfly Network, Inc.
  • Clarius Mobile Health Corp.
  • EchoNous, Inc.
  • Sonoscanner SAS
  • Telemed Medical Systems S.r.l.
  • Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
  • Hitachi, Ltd.
  • Konica Minolta, Inc.
  • Healcerion Co., Ltd.
  • Exo Imaging, Inc.
  • RoboMedical Co., Ltd.
  • ESAOTE S.p.A.
  • Intelligent Ultrasound Group plc
  • Terason Division, Teratech Corporation

Recent Developments

  • GE HealthCare announced a strategic partnership with NVIDIA in April 2025 to co‑develop autonomous imaging systems, targeting both X‑ray and ultrasound modalities, and emphasizing AI‑driven workflow automation for clinical environments. The collaboration aims to integrate deep learning algorithms into hardware platforms, reduce operator dependence, and accelerate diagnostic throughput across hospitals and point‑of‑care settings.
  • In March 2025 GE HealthCare outlined its roadmap to deliver AI‑powered X‑ray and ultrasound solutions, highlighting autonomous scanning capabilities that enable real‑time image acquisition without manual probe manipulation, thereby improving consistency and expanding access to advanced imaging in diverse clinical workflows. The initiative also targets integration with existing hospital information systems to streamline data flow and support AI‑assisted diagnosis.
  • GE HealthCare continued to showcase autonomous ultrasound advancements in the 2026 ultrasound market round‑up released in January 2026, where its AI‑enhanced devices were cited among leading innovations driving point‑of‑care diagnostics and operator‑independent imaging. These highlights underscored the company's commitment to reducing examination time and expanding accessibility of high‑quality ultrasound across varied care settings.

Autonomous Ultrasound Guidance Key Market Trends

Autonomous Ultrasound Guidance Market SkyQuest Analysis

SkyQuest’s ABIRAW (Advanced Business Intelligence, Research & Analysis Wing) is our Business Information Services team that Collects, Collates, Correlates, and Analyses the Data collected by means of Primary Exploratory Research backed by robust Secondary Desk research. As per SkyQuest analysis, the autonomous ultrasound guidance market is being propelled primarily by the surge in point‑of‑care imaging demand, which enables bedside diagnostics and reduces reliance on central imaging suites, a second strong driver is rapid progress in AI‑driven navigation algorithms that improve real‑time landmark detection and probe positioning. The AI‑Based Image Guidance segment leads the market because it directly tackles real‑time anatomical interpretation, while North America remains the dominant region thanks to its mature health‑care ecosystem, supportive reimbursement and early‑adopter hospitals. However, high initial capital investment continues to restrain broader uptake, especially in resource‑constrained settings, tempering the overall growth pace.

Report Metric Details
Market size value in 2024 USD 1.28 Billion
Market size value in 2033 USD 5.99 Billion
Growth Rate 18.7%
Base year 2024
Forecast period (2026-2033)
Forecast Unit (Value) USD Billion
Segments covered
  • Offering
    • Hardware
    • Software
    • Services
  • Technology
    • AI-Based Image Guidance
    • Robotic Ultrasound Guidance
    • Navigation & Tracking Systems
  • Application
    • Diagnostic Imaging
    • Interventional Procedures
    • Obstetrics & Gynecology
    • Cardiology
    • Musculoskeletal Imaging
    • Emergency & Critical Care
  • End User
    • Hospitals
    • Diagnostic Imaging Centers
    • Ambulatory Surgical Centers
    • Research & Academic Institutes
Regions covered North America (US, Canada), Europe (Germany, France, United Kingdom, Italy, Spain, Rest of Europe), Asia Pacific (China, India, Japan, Rest of Asia-Pacific), Latin America (Brazil, Rest of Latin America), Middle East & Africa (South Africa, GCC Countries, Rest of MEA)
Companies covered
  • GE HealthCare Technologies Inc.
  • Siemens Healthineers AG
  • Koninklijke Philips N.V.
  • Canon Medical Systems Corporation
  • Fujifilm Holdings Corporation
  • Samsung Medison Co., Ltd.
  • Butterfly Network, Inc.
  • Clarius Mobile Health Corp.
  • EchoNous, Inc.
  • Sonoscanner SAS
  • Telemed Medical Systems S.r.l.
  • Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
  • Hitachi, Ltd.
  • Konica Minolta, Inc.
  • Healcerion Co., Ltd.
  • Exo Imaging, Inc.
  • RoboMedical Co., Ltd.
  • ESAOTE S.p.A.
  • Intelligent Ultrasound Group plc
  • Terason Division, Teratech Corporation
Customization scope

Free report customization with purchase. Customization includes:-

  • Segments by type, application, etc
  • Company profile
  • Market dynamics & outlook
  • Region

To get a free trial access to our platform which is a one stop solution for all your data requirements for quicker decision making. This platform allows you to compare markets, competitors who are prominent in the market, and mega trends that are influencing the dynamics in the market. Also, get access to detailed SkyQuest exclusive matrix.

Table Of Content

Executive Summary

Market overview

  • Exhibit: Executive Summary – Chart on Market Overview
  • Exhibit: Executive Summary – Data Table on Market Overview
  • Exhibit: Executive Summary – Chart on Autonomous Ultrasound Guidance Market Characteristics
  • Exhibit: Executive Summary – Chart on Market by Geography
  • Exhibit: Executive Summary – Chart on Market Segmentation
  • Exhibit: Executive Summary – Chart on Incremental Growth
  • Exhibit: Executive Summary – Data Table on Incremental Growth
  • Exhibit: Executive Summary – Chart on Vendor Market Positioning

Parent Market Analysis

Market overview

Market size

  • Market Dynamics
    • Exhibit: Impact analysis of DROC, 2021
      • Drivers
      • Opportunities
      • Restraints
      • Challenges
  • SWOT Analysis

KEY MARKET INSIGHTS

  • Technology Analysis
    • (Exhibit: Data Table: Name of technology and details)
  • Pricing Analysis
    • (Exhibit: Data Table: Name of technology and pricing details)
  • Supply Chain Analysis
    • (Exhibit: Detailed Supply Chain Presentation)
  • Value Chain Analysis
    • (Exhibit: Detailed Value Chain Presentation)
  • Ecosystem Of the Market
    • Exhibit: Parent Market Ecosystem Market Analysis
    • Exhibit: Market Characteristics of Parent Market
  • IP Analysis
    • (Exhibit: Data Table: Name of product/technology, patents filed, inventor/company name, acquiring firm)
  • Trade Analysis
    • (Exhibit: Data Table: Import and Export data details)
  • Startup Analysis
    • (Exhibit: Data Table: Emerging startups details)
  • Raw Material Analysis
    • (Exhibit: Data Table: Mapping of key raw materials)
  • Innovation Matrix
    • (Exhibit: Positioning Matrix: Mapping of new and existing technologies)
  • Pipeline product Analysis
    • (Exhibit: Data Table: Name of companies and pipeline products, regional mapping)
  • Macroeconomic Indicators

COVID IMPACT

  • Introduction
  • Impact On Economy—scenario Assessment
    • Exhibit: Data on GDP - Year-over-year growth 2016-2022 (%)
  • Revised Market Size
    • Exhibit: Data Table on Autonomous Ultrasound Guidance Market size and forecast 2021-2027 ($ million)
  • Impact Of COVID On Key Segments
    • Exhibit: Data Table on Segment Market size and forecast 2021-2027 ($ million)
  • COVID Strategies By Company
    • Exhibit: Analysis on key strategies adopted by companies

MARKET DYNAMICS & OUTLOOK

  • Market Dynamics
    • Exhibit: Impact analysis of DROC, 2021
      • Drivers
      • Opportunities
      • Restraints
      • Challenges
  • Regulatory Landscape
    • Exhibit: Data Table on regulation from different region
  • SWOT Analysis
  • Porters Analysis
    • Competitive rivalry
      • Exhibit: Competitive rivalry Impact of key factors, 2021
    • Threat of substitute products
      • Exhibit: Threat of Substitute Products Impact of key factors, 2021
    • Bargaining power of buyers
      • Exhibit: buyers bargaining power Impact of key factors, 2021
    • Threat of new entrants
      • Exhibit: Threat of new entrants Impact of key factors, 2021
    • Bargaining power of suppliers
      • Exhibit: Threat of suppliers bargaining power Impact of key factors, 2021
  • Skyquest special insights on future disruptions
    • Political Impact
    • Economic impact
    • Social Impact
    • Technical Impact
    • Environmental Impact
    • Legal Impact

Market Size by Region

  • Chart on Market share by geography 2021-2027 (%)
  • Data Table on Market share by geography 2021-2027(%)
  • North America
    • Chart on Market share by country 2021-2027 (%)
    • Data Table on Market share by country 2021-2027(%)
    • USA
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • Canada
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
  • Europe
    • Chart on Market share by country 2021-2027 (%)
    • Data Table on Market share by country 2021-2027(%)
    • Germany
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • Spain
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • France
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • UK
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • Rest of Europe
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
  • Asia Pacific
    • Chart on Market share by country 2021-2027 (%)
    • Data Table on Market share by country 2021-2027(%)
    • China
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • India
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • Japan
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • South Korea
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • Rest of Asia Pacific
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
  • Latin America
    • Chart on Market share by country 2021-2027 (%)
    • Data Table on Market share by country 2021-2027(%)
    • Brazil
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • Rest of South America
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
  • Middle East & Africa (MEA)
    • Chart on Market share by country 2021-2027 (%)
    • Data Table on Market share by country 2021-2027(%)
    • GCC Countries
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • South Africa
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)
    • Rest of MEA
      • Exhibit: Chart on Market share 2021-2027 (%)
      • Exhibit: Market size and forecast 2021-2027 ($ million)

KEY COMPANY PROFILES

  • Competitive Landscape
    • Total number of companies covered
      • Exhibit: companies covered in the report, 2021
    • Top companies market positioning
      • Exhibit: company positioning matrix, 2021
    • Top companies market Share
      • Exhibit: Pie chart analysis on company market share, 2021(%)

Methodology

For the Autonomous Ultrasound Guidance Market, our research methodology involved a mixture of primary and secondary data sources. Key steps involved in the research process are listed below:

1. Information Procurement: This stage involved the procurement of Market data or related information via primary and secondary sources. The various secondary sources used included various company websites, annual reports, trade databases, and paid databases such as Hoover's, Bloomberg Business, Factiva, and Avention. Our team did 45 primary interactions Globally which included several stakeholders such as manufacturers, customers, key opinion leaders, etc. Overall, information procurement was one of the most extensive stages in our research process.

2. Information Analysis: This step involved triangulation of data through bottom-up and top-down approaches to estimate and validate the total size and future estimate of the Autonomous Ultrasound Guidance Market.

3. Report Formulation: The final step entailed the placement of data points in appropriate Market spaces in an attempt to deduce viable conclusions.

4. Validation & Publishing: Validation is the most important step in the process. Validation & re-validation via an intricately designed process helped us finalize data points to be used for final calculations. The final Market estimates and forecasts were then aligned and sent to our panel of industry experts for validation of data. Once the validation was done the report was sent to our Quality Assurance team to ensure adherence to style guides, consistency & design.

Analyst Support

Customization Options

With the given market data, our dedicated team of analysts can offer you the following customization options are available for the Autonomous Ultrasound Guidance Market:

Product Analysis: Product matrix, which offers a detailed comparison of the product portfolio of companies.

Regional Analysis: Further analysis of the Autonomous Ultrasound Guidance Market for additional countries.

Competitive Analysis: Detailed analysis and profiling of additional Market players & comparative analysis of competitive products.

Go to Market Strategy: Find the high-growth channels to invest your marketing efforts and increase your customer base.

Innovation Mapping: Identify racial solutions and innovation, connected to deep ecosystems of innovators, start-ups, academics, and strategic partners.

Category Intelligence: Customized intelligence that is relevant to their supply Markets will enable them to make smarter sourcing decisions and improve their category management.

Public Company Transcript Analysis: To improve the investment performance by generating new alpha and making better-informed decisions.

Social Media Listening: To analyze the conversations and trends happening not just around your brand, but around your industry as a whole, and use those insights to make better Marketing decisions.

$5,300

REQUEST FOR SAMPLE

Please verify that you're not a robot to proceed!
Want to customize this report? REQUEST FREE CUSTOMIZATION

FAQs

Global Autonomous Ultrasound Guidance Market size was valued at USD 1.28 Billion in 2024 and is poised to grow from USD 1.52 Billion in 2025 to USD 5.99 Billion by 2033, growing at a CAGR of 18.7% during the forecast period (2026-2033).

The competitive landscape is shaped by rapid tech innovation and strategic alliances, with leading firms pursuing M&A to integrate AI imaging capabilities, partnering with hospital networks for clinical validation, and launching autonomous scanning robots to differentiate offerings in a market driven by demand for precision diagnostics. Recent collaborations between AI‑focused startups and established device manufacturers illustrate how joint development accelerates time‑to‑market for next‑generation autonomous ultrasound solutions. 'GE HealthCare Technologies Inc.', 'Siemens Healthineers AG', 'Koninklijke Philips N.V.', 'Canon Medical Systems Corporation', 'Fujifilm Holdings Corporation', 'Samsung Medison Co., Ltd.', 'Butterfly Network, Inc.', 'Clarius Mobile Health Corp.', 'EchoNous, Inc.', 'Sonoscanner SAS', 'Telemed Medical Systems S.r.l.', 'Shenzhen Mindray Bio-Medical Electronics Co., Ltd.', 'Hitachi, Ltd.', 'Konica Minolta, Inc.', 'Healcerion Co., Ltd.', 'Exo Imaging, Inc.', 'RoboMedical Co., Ltd.', 'ESAOTE S.p.A.', 'Intelligent Ultrasound Group plc', 'Terason Division, Teratech Corporation'

Healthcare providers are increasingly adopting autonomous ultrasound systems to deliver diagnostics at the bedside, reducing reliance on centralized imaging facilities. This shift enables clinicians to obtain immediate visual feedback, thereby improving patient throughput and clinical decision‑making. The convenience of point‑of‑care imaging also supports resource‑limited environments where traditional ultrasound expertise may be scarce, fostering broader acceptance of autonomous guidance technology across diverse care settings. Consequently, hospitals view autonomous ultrasound as a strategic asset that aligns with initiatives to enhance operational efficiency while maintaining diagnostic quality, prompting increased procurement and integration efforts.

Ai‑Driven Real‑Time Imaging: The integration of advanced artificial intelligence algorithms enables autonomous ultrasound systems to interpret and adjust imaging parameters instantly, delivering consistently high‑quality diagnostic views without operator intervention. Clinicians benefit from reduced scan times and improved accuracy, while hospitals experience streamlined workflows and lower reliance on highly specialized sonographers. This capability is driving wider adoption across emergency departments, intensive care units, and remote telemedicine settings, where rapid, reliable imaging is critical for timely patient management and better clinical outcomes.

Why does North America Dominate the Global Autonomous Ultrasound Guidance Market? |@12
AGC3x.webp
Aisin3x.webp
ASKA P Co. LTD3x.webp
BD3x.webp
BILL & MELIDA3x.webp
BOSCH3x.webp
CHUNGHWA TELECOM3x.webp
DAIKIN3x.webp
DEPARTMENT OF SCIENCE & TECHNOLOGY3x.webp
ETRI3x.webp
Fiti Testing3x.webp
GERRESHEIMER3x.webp
HENKEL3x.webp
HITACHI3x.webp
HOLISTIC MEDICAL CENTRE3x.webp
Institute for information industry3x.webp
JAXA3x.webp
JTI3x.webp
Khidi3x.webp
METHOD.3x.webp
Missul E&S3x.webp
MITSUBISHI3x.webp
MIZUHO3x.webp
NEC3x.webp
Nippon steel3x.webp
NOVARTIS3x.webp
Nttdata3x.webp
OSSTEM3x.webp
PALL3x.webp
Panasonic3x.webp
RECKITT3x.webp
Rohm3x.webp
RR KABEL3x.webp
SAMSUNG ELECTRONICS3x.webp
SEKISUI3x.webp
Sensata3x.webp
SENSEAIR3x.webp
Soft Bank Group3x.webp
SYSMEX3x.webp
TERUMO3x.webp
TOYOTA3x.webp
UNDP3x.webp
Unilever3x.webp
YAMAHA3x.webp
Yokogawa3x.webp

Want to customize this report? This report can be personalized according to your needs. Our analysts and industry experts will work directly with you to understand your requirements and provide you with customized data in a short amount of time. We offer $1000 worth of FREE customization at the time of purchase.

Feedback From Our Clients